Period covered: 30 June 2026 vs 30 September 2026 (Q2 FY2026-27)
The INR zero-coupon yield curve shifted up across all tenors from 0.5 years onwards, reversing most of the previous quarter’s decline. The rise was largest at the 2–3 year point (about 47–48 bps), moderating to roughly 34–35 bps at the 18–20 year segment, while the 0-year rate was broadly unchanged (-3 bps). The 1-to-20 year spread was unchanged at 1.73%. For AS 15 / Ind AS 19 valuations, discount rates at 30 September 2026 are higher than at 30 June 2026 at every tenor from 0.5 years, so, all else equal, employee benefit obligations will be lower than at the June 2026 valuation.
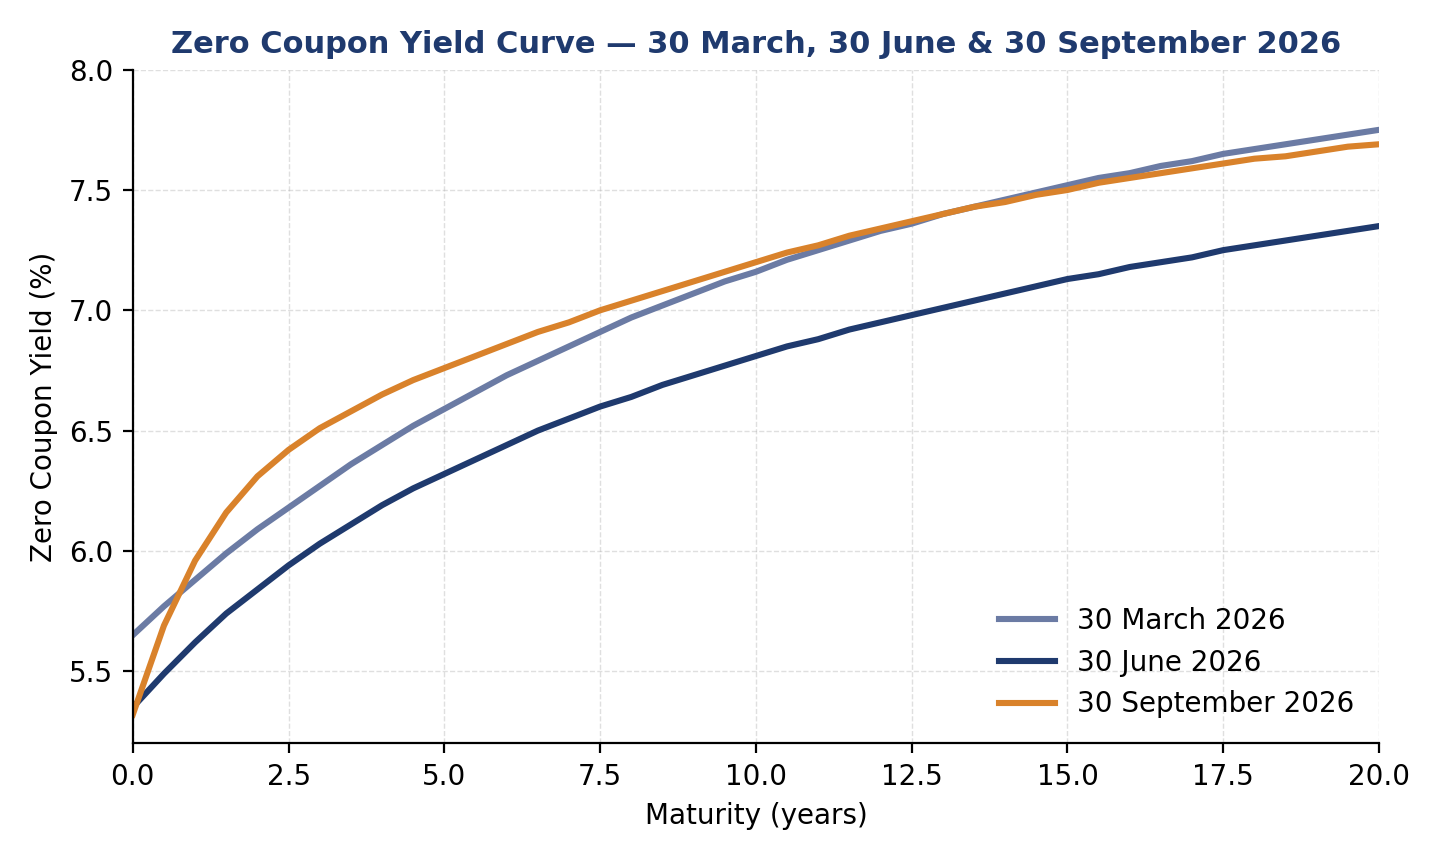
Zero Coupon Yield Rates (%) – Maturities up to 20 Years
|
|
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Source: CCIL zero-coupon yield curve, rates as at 30 June 2026 and 30 September 2026. Δ (bps) = change in yield from June to September (positive = increase, negative = decline). The full PDF report also covers the comparison with March 2026, implications for AS 15 / Ind AS 19 valuations and extended tenors up to 50 years.